
Date: September 2026 Written by: Nicola Beswick, Founder & Certified Financial Planner®
Quick summary: Money given to your kids in their 20s or 30s does far more than the same money left in a will at 55. But before you gift, check your own retirement first, know Centrelink's gifting limits ($10,000 a year, $30,000 over five years), and decide whether it's a gift or a loan.
You've worked hard. You've got some money behind you. And your kids are watching Melbourne house prices run further away every year.
You want to help. But not if it means jeopardising your financial future or creates tension in the family.
In an article in the Australian Financial Review, Nicola Beswick shared her thinking on gifting, and the financial benefits to the next generation when wealth is transferred at the right time and structured the right way.
The AFR piece, Why $100k at 25 is more powerful than an inheritance at 55, makes a thought-provoking point. Most inheritances arrive after 55, when the big financial hurdles have passed. Give the same money decades earlier, when it's actually needed, and it can make a life-changing difference. The right life stage can matter more than the amount.

The warm hand
There's an old saying about giving with a warm hand rather than a cold one. It means giving while you're alive, not through your will.
Think of an inheritance as a torch handed over after the race has been run. A gift now is passing the torch while they're still on the track. Same torch. Completely different result.
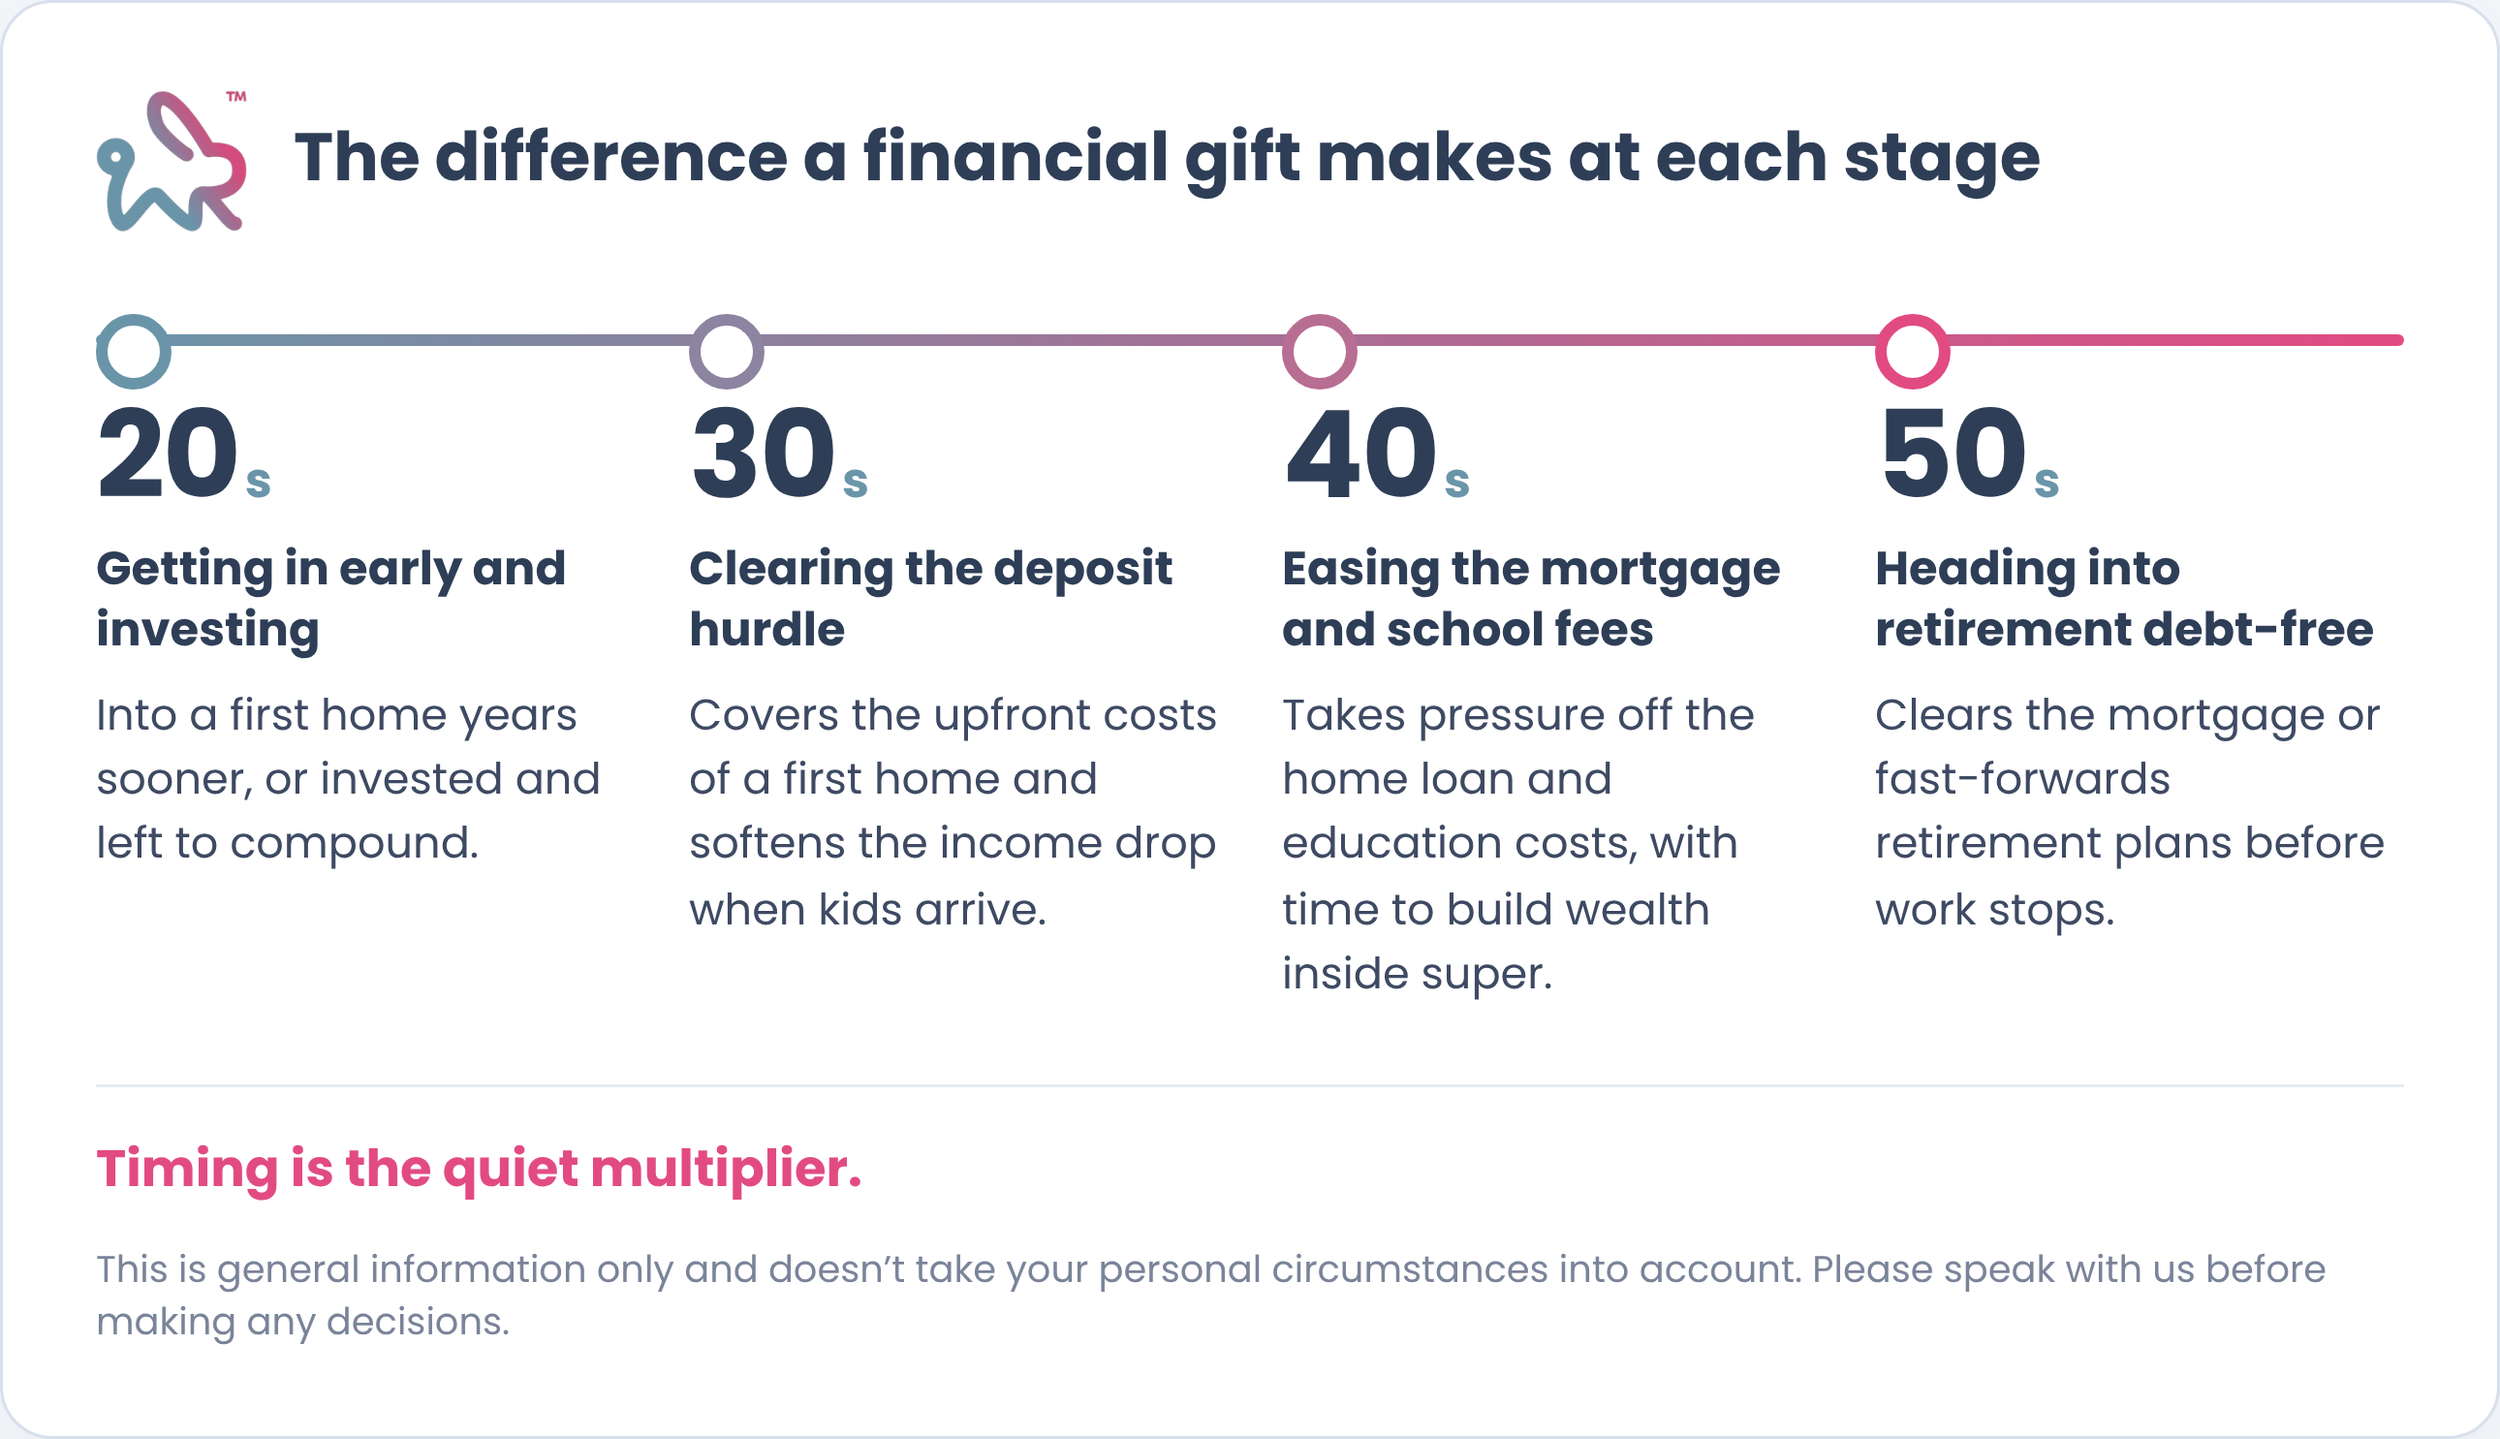
The difference a financial gift makes at each stage
20s: Getting in early and investing
At this age the goal is usually a first home, and the deposit is the wall. A gift gets them over it years earlier. Not the forever home. An entry-level apartment or townhouse that builds equity they can use later.
And if they're not ready to buy, the money can be invested and left to grow. The best thing about starting early is compounding. Nicola recently helped a client in their early 20s do exactly that with an early inheritance, using low-cost exchange-traded funds.
30s: Clearing the deposit hurdle
The average Australian first home buyer is now in their mid-30s, and upfront costs are the biggest reason. A gift covers the deposit and stamp duty they'd otherwise spend years saving for. It's also the decade when kids arrive, so a gift can soften the hit of one parent's income dropping out.
40s: Easing the mortgage and school fees
Mortgage, school fees, cost of living, and retirement starting to feel real. Every dollar counts. A lump sum on the mortgage, or help with school fees, takes real pressure off. It's also a good time to start building wealth inside super, because there's still 20 years for it to grow.
50s: Heading into retirement debt-free
The kids have left home and retirement is on the horizon. A gift here can fast-forward retirement plans or clear a mortgage that was going to drag into retirement. With people living longer, that stability matters more than ever.
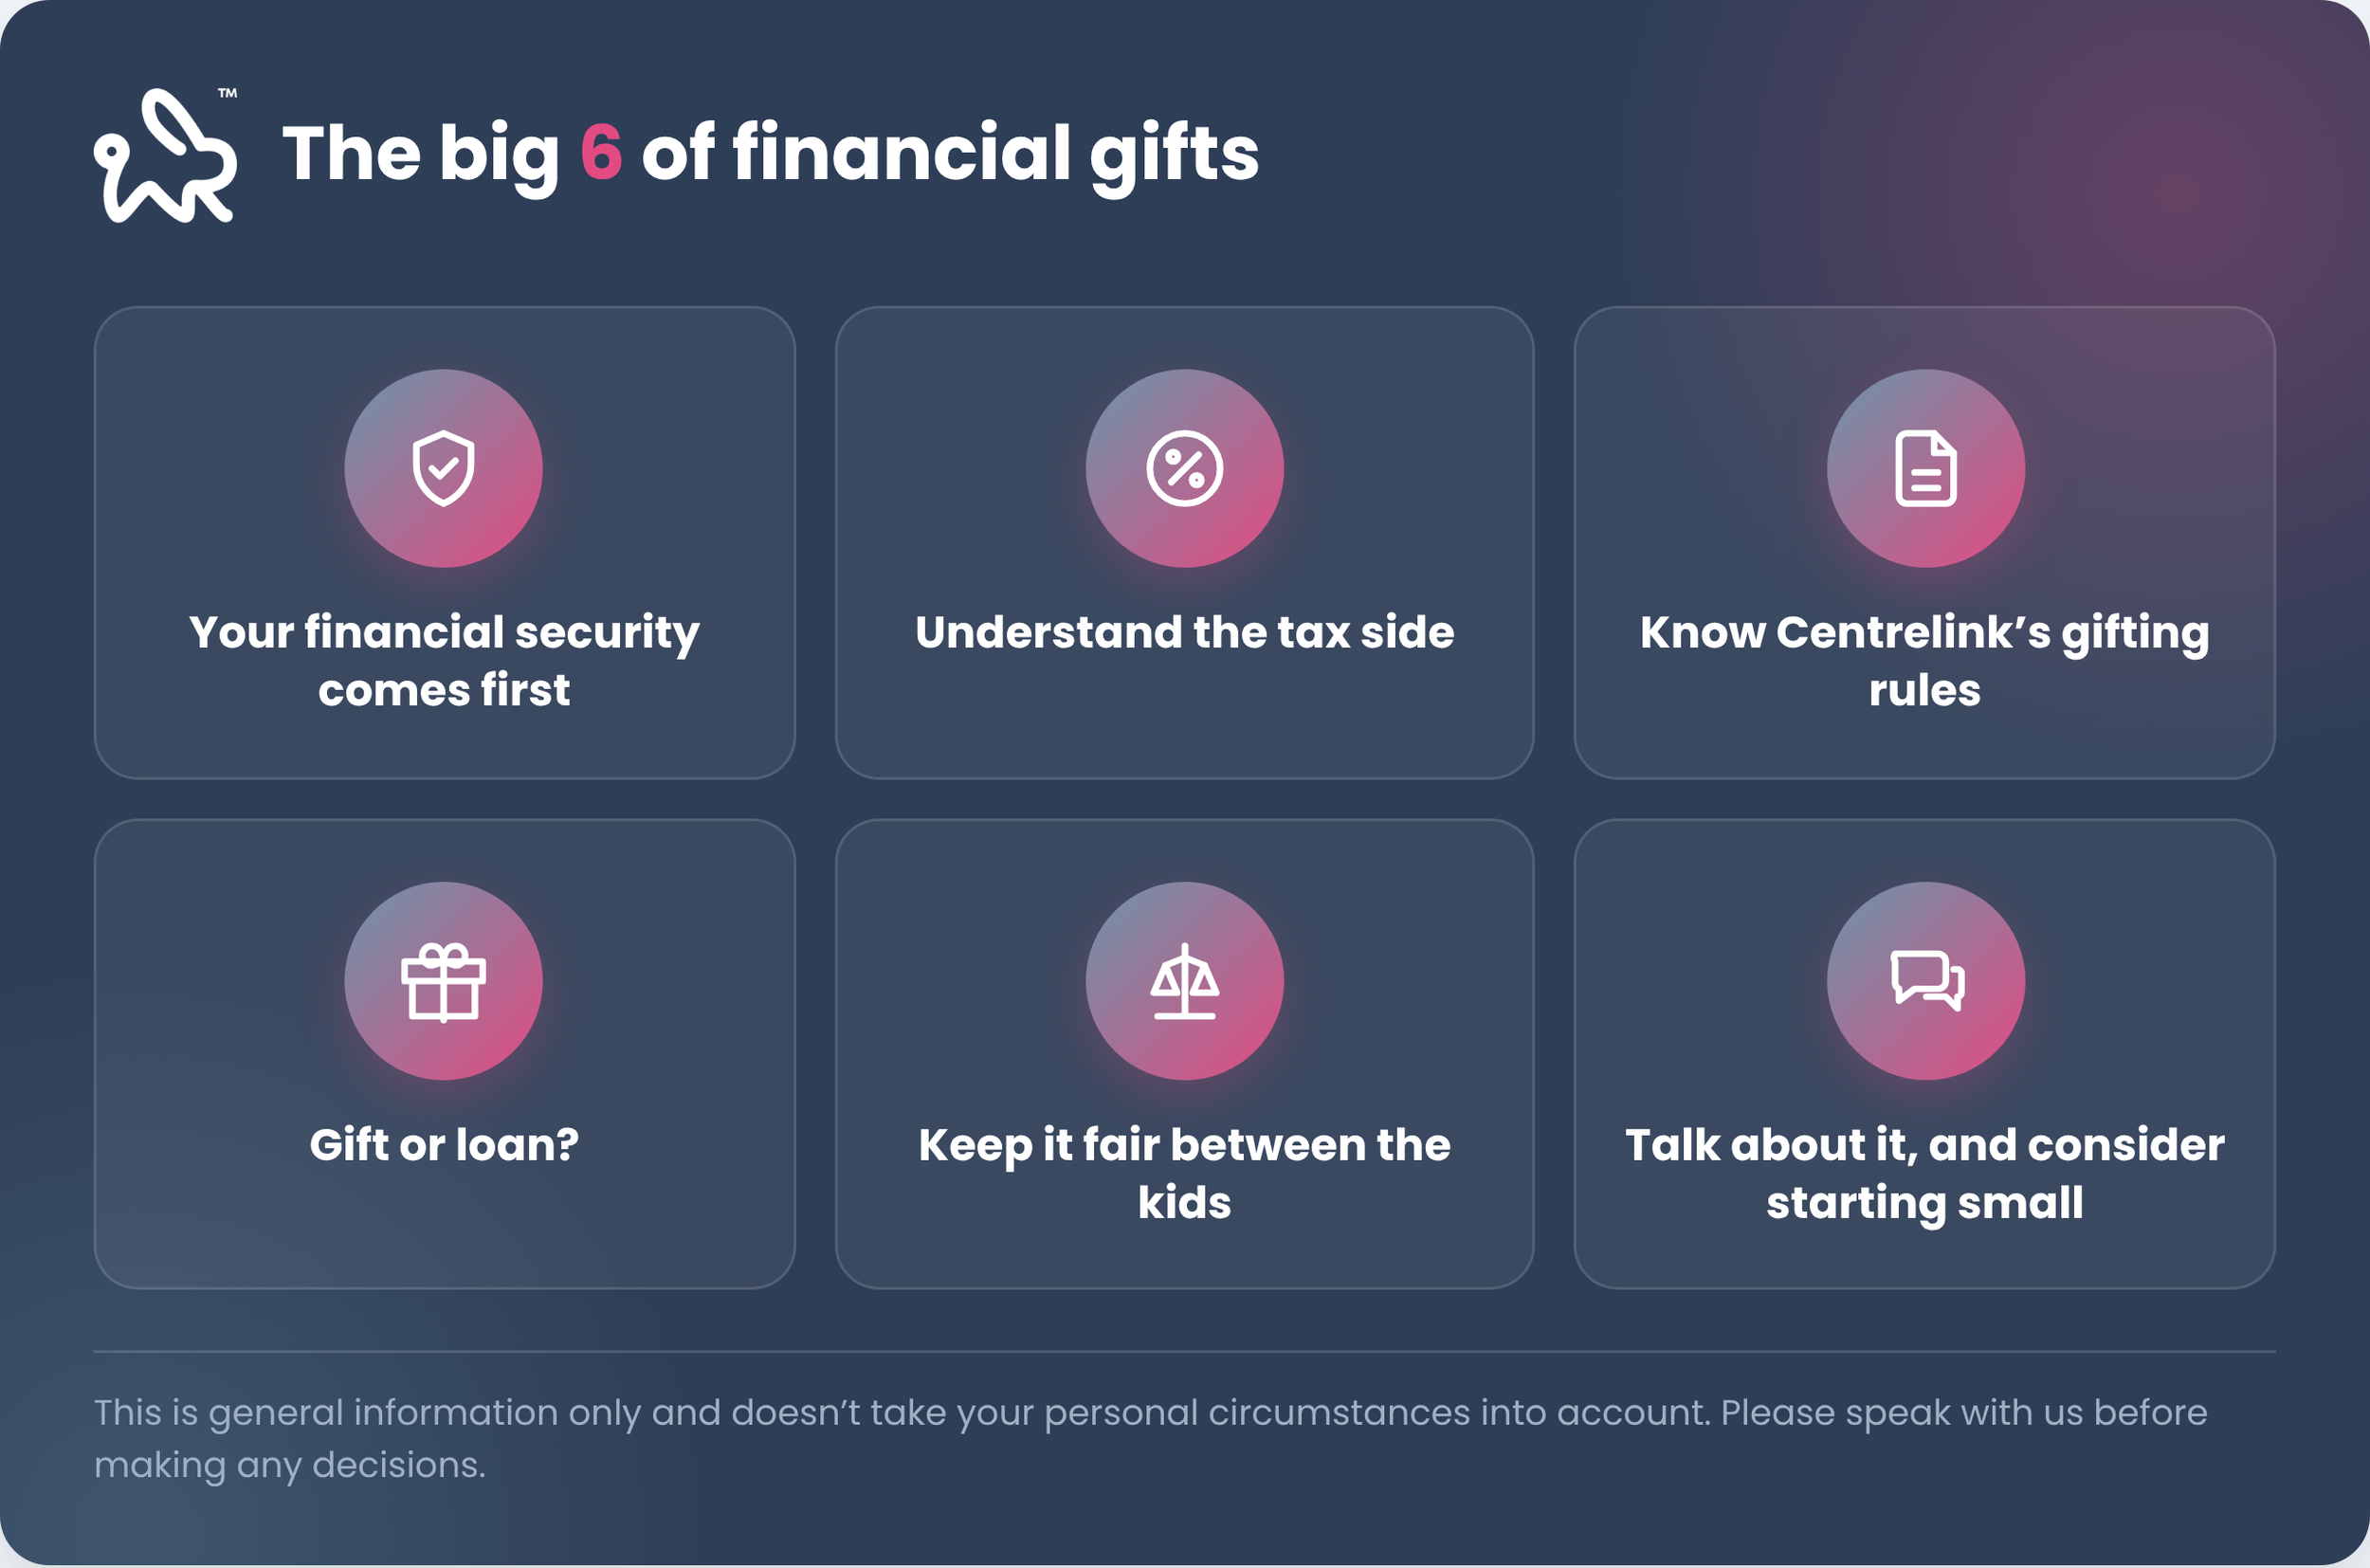
Six things to think about before gifting money
Transferring wealth to the younger generation while you're around to see them benefit from it can make an enduring difference. But it still needs careful planning. These are the six things we work through with clients before any money changes hands.
1. Your financial security comes first
You can't help your kids if you've undermined your own retirement. People are living longer, which means more years to fund and a real chance of aged care costs down the track. We model your future first, then show you what you can comfortably give. Generosity works best when it's built on a plan.
2. Understand the tax side
There's no gift tax in Australia, and your kids won't pay income tax on cash you give them. The tax question is on your side, in how you fund the gift.
Sell shares or an investment property to raise the money and capital gains tax applies to the sale. Give the asset itself instead of cash and it's still a CGT event for you, valued at market price. Money drawn from super after 60 is generally tax-free, which can make it the cleanest source, as long as there's enough left for your own retirement.
3. Know Centrelink's gifting rules
This one catches people out. If you're on the Age Pension, or within five years of reaching Age Pension age, Services Australia lets you gift up to $10,000 in a financial year, and no more than $30,000 over five financial years.
Give more than that and Centrelink still counts the excess as your asset, and deems income on it, for five years from the date of the gift. In plain terms, you've given the money away but you're assessed as if you still have it. That can reduce your pension and flow into aged care means testing too.
Nobody stops you giving. The rules only decide how the gift is treated when working out your entitlements. If you're more than five years from pension age, they don't apply at all. Timing matters.
4. Gift or loan?
A gift is gone. A properly documented loan can come back if things go wrong, like your child's relationship ending. For larger amounts, a written loan agreement with clear terms is often the smarter structure, and it's worth getting legal advice before the money moves.
One thing to know. Simply calling it a loan doesn't protect it. The paperwork has to be real. "We'll sort it out later" is how family fallouts start.
5. Keep it fair between the kids
Helping one child now and not the others isn't wrong. Silence about it is. Talk openly, or square it up in your will so nobody feels short-changed later. Resentment grows in the dark.
6. Talk about it, and consider starting small
Gifts are usually informal, and that's where expectations drift apart. Agree on what the money is for before you hand it over. And if you're nervous about how it'll be used, you don't have to start with $100,000. Try $10,000 and see what they do with it.
The bottom line
Helping your kids while you're around to see it can change the course of their lives. The trick is doing it without putting your own future at risk. At White Rabbit Advisory, we look at your retirement, your pension position and what aged care might cost one day. Then we show you how much you can gift to your children or grandchildren, how to structure it tax-effectively, the timing, and what it does to your Centrelink position.
If you're working through an inheritance of your own, or planning your retirement, gifting often fits into that bigger picture.
About White Rabbit Advisory
White Rabbit Advisory is a Melbourne financial planning practice helping people through life's biggest twists and turns with straight talk, real care and a firm no-judgement policy. We cut through the complexity so you can make confident decisions about your money, and your life.
Headstrong, heartfelt and here for you.
FAQs
-
You can gift up to $10,000 in a financial year and $30,000 over five financial years without it affecting your Age Pension. Anything above that is counted as your asset and deemed income for five years. The rules apply if you're on the pension or within five years of pension age. Outside that window, there are no limits.
-
For most families, transferring wealth earlier does more good, as long as your own retirement is secure. Money received in the 20s or 30s can buy a home sooner or compound for decades.
An inheritance at 55 or older usually arrives after the hardest financial years have passed. The answer depends on what you can afford to give without risking your own future.
-
No. Australia has no gift tax, and a cash gift isn't income for the person receiving it.
However, any earnings they make from investing the money are taxed in the usual way. If you're gifting assets like shares or property rather than cash, capital gains tax can apply to you, so get advice first.
-
A documented loan offers more protection, especially for larger amounts.
If your child's relationship breaks down, a gift is usually treated as part of their shared assets, while a genuine loan can be repaid. The agreement needs to be in writing, with clear terms, and ideally reviewed by a lawyer.
-
Yes. The same gifting rules that apply to the Age Pension are used when your aged care fees are assessed. Gifts above the free limits are counted as your asset for five years. That can increase what you're asked to pay for care, so it's worth planning gifts with aged care in mind.
-
Give what you can afford after your own retirement is funded, not what you think they need. For many Melbourne families, enough to cover stamp duty and lift the deposit above 5 per cent makes a real difference. A financial adviser can model what's affordable for you and what it does to your pension.
-
Yes. Centrelink's gifting rules apply to gifts to anyone, including grandchildren. The $10,000 and $30,000 limits cover all your gifts combined, not per person. Gifts for school fees or a first home are common and worthwhile. Just keep track of the totals across each financial year.
White Rabbit Advisory Pty Ltd is a registered tax (financial) adviser and any reference to tax advice contained in this document is incidental to the general financial advice it may contain. You should seek specialist advice from a tax professional to confirm the impact of this advice on your overall tax position. You should obtain financial advice relevant to your circumstances before making financial decisions. Whilst every care has been taken in the preparation of this information, it may not remain current after the date of publication and White Rabbit Advisory Pty Ltd and its related bodies make no representation as to its accuracy or completeness.
Published: October 2026 © Copyright 2026
White Rabbit Advisory Pty Ltd (ABN 54 676 177 138) is a Corporate Authorised Representative (No. 1314020) of Personal Financial Services Ltd (ABN 26 098 725 145). Australian Financial Services Licence (No 234459).
Join Curiouser
Your monthly dose of financial wisdom delivered with 🩷.
→ Plain English takes on the headlines and rule changes.
→ Insider strategies that quietly make a huge difference to your future.
→ Real stories of clients living life on the other side of a big transition.